A building can be insured and still be underinsured
If the policy limit doesn’t reflect the true cost of demolition, professional fees, compliance and rebuilding, owners may be left to fund the shortfall. This is why current building valuations matter to owners corporations, committees and strata managers across Australia.
The Australian market in three numbers
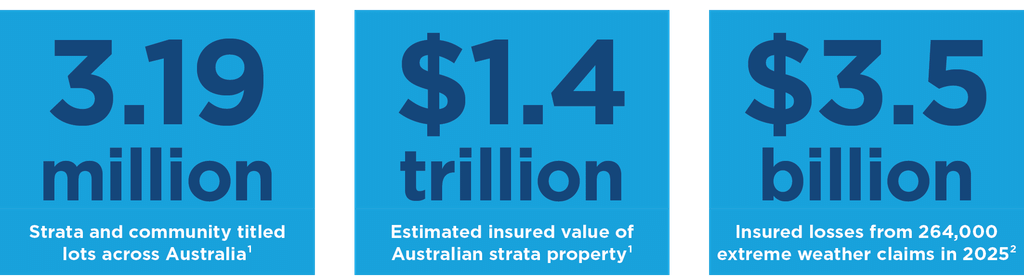
Australia now has more than 368,000 strata schemes.¹ At the same time, residential construction costs continued to rise through 2025, increasing 2.5% over the year to December after a 1.0% rise in the final quarter.³ Slower growth does not mean lower rebuilding costs. It means already elevated costs are still moving upward.
What a valuation should capture
A strata insurance valuation estimates the cost to reinstate the insured property after a major loss. It is not the market value of the lots and it is not simply the original construction cost indexed each year.
- Demolition and debris removal
- Labour, materials and contractor costs
- Architects, engineers, surveyors and other professional fees
- Current building standards and compliance upgrades
- Cost escalation during design and reconstruction
- Common property, shared services and relevant improvements
Where the exposure sits
If the building sum insured is too low, a major claim may exhaust the available policy limit before the property is fully reinstated. Depending on the policy and circumstances, this can lead to:
- Special levies or other owner funding
- Delays while the funding gap is resolved
- Pressure on owners who cannot readily meet an unexpected levy
- Disputes about earlier committee decisions
- Greater scrutiny of the records and advice relied upon
When should the valuation be reviewed?
- Within the period required by the applicable legislation
- After major works, additions or redevelopment
- After material changes to the building or its use
- When construction costs or compliance requirements move significantly
- Where the existing valuation no longer reflects the property
Who does what?
- Owners corporation or body corporate Makes the insurance decision and is generally responsible for maintaining the required building cover.
- Committee Considers the valuation and broker advice, asks questions and records the reasons for its decision.
- Strata manager Coordinates the valuation and renewal information, places decisions before the committee and keeps clear records.
- Insurance broker Explains the insurance implications, approaches insurers and provides a recommendation based on the available information.
- Valuer Provides an independent estimate of the reinstatement cost. The valuer does not set the premium or select the insurer.
A practical governance approach
- Obtain the valuation early enough for renewal discussions
- Give the complete report to the broker, not only the headline figure
- Check whether the policy adds escalation, catastrophe or other allowances
- Minute the decision and any reasons for departing from professional advice
- Explain material changes to owners in plain English
As soon as a valuation is received, the owners corporation or strata manager should provide the complete report to the insurance broker. This allows the updated figure to be considered against the current cover and factored into renewal discussions without delay.
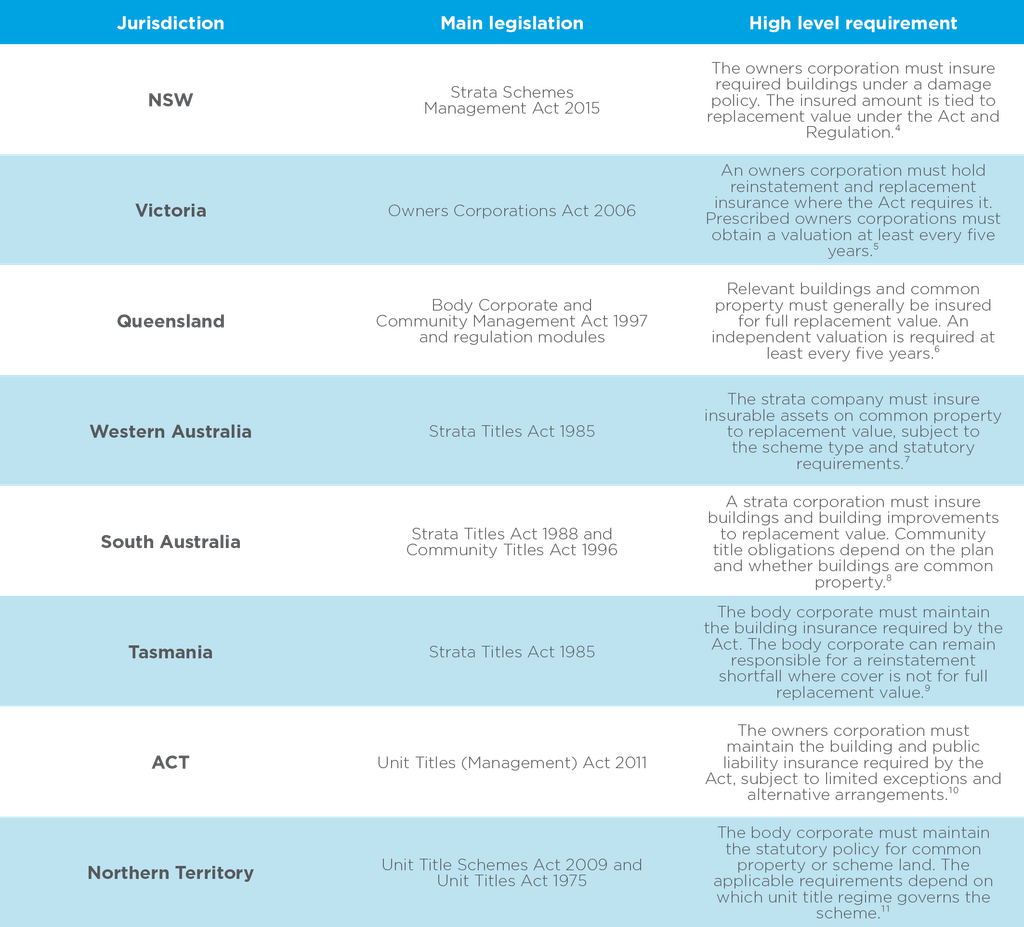
Insurance obligations across Australia
Each jurisdiction uses different terminology and rules. The summary below is a high level guide only. It does not replace scheme specific legal or insurance advice.
The question is not whether a valuation increases the premium
The real question is whether the building could be rebuilt if a major loss occurred. Reducing the building sum insured may lower part of the premium, but it transfers more financial risk back to owners. A current valuation gives the committee, strata manager and broker a defensible basis for the renewal decision.
Committee checklist
- Is the valuation current?
- Has the full report been reviewed?
- Are major works included?
- Is the decision minuted?
Achieving the best strata insurance outcome
Whitbread recommend that strata managers advise their clients to obtain a professional property valuation by a sworn valuer every three to five years, ensuring the building remains adequately insured, and adjust insurance coverage accordingly. Please contact your Whitbread insurance broker if you would like to know more about the valuations or to discuss a particular risk in greater detail.
Download a PDF of our article here
T: 1300 424 627
E: info@whitbread.com.au

Important notice
This article provides information rather than financial product or other advice. The content of this article, including any information contained in it, has been prepared without taking into account your objectives, financial situation or needs. You should consider the appropriateness of the information, taking these matters into account, before you act on any information. In particular, you should review the product disclosure statement for any product that the information relates to before acquiring the product.
Information is current as at the date the article is written as specified within it but is subject to change. Whitbread Insurance Brokers make no representation as to the accuracy or completeness of the information. Various third parties have contributed to the production of this content. All information is subject to copyright and may not be reproduced without the prior written consent of Whitbread Insurance Brokers.
This article is not intended to be personal advice and you should not rely on it as a substitute for any form of personal advice. Please contact Whitbread Associates Pty Ltd ABN 69 005 490 228, License Number 229092 trading as Whitbread Insurance Brokers for further information or refer to our website.
Footnotes
1 UNSW City Futures Research Centre, 2024 Australasian Strata Insights; national figures reported as 368,234 schemes, 3,191,244 lots and approximately $1.4 trillion insured value.
2 Insurance Council of Australia, Extreme weather cost $3.5 billion in 2025, 23 January 2026.
3 Cotality, Cordell Construction Cost Index, December quarter 2025; 1.0% quarterly and 2.5% annual growth.
4 Strata Schemes Management Act 2015 (NSW), Part 9, and Strata Schemes Management Regulation 2016 (NSW).
5 Owners Corporations Act 2006 (Vic), insurance and valuation provisions.
6 Queensland body corporate regulation modules, insurance and valuation provisions.
7 Strata Titles Act 1985 (WA), Part 8.
8 Strata Titles Act 1988 (SA), s 30, and Community Titles Act 1996 (SA).
9 Strata Titles Act 1998 (Tas).
10 Unit Titles (Management) Act 2011 (ACT).
11 Unit Title Schemes Act 2009 (NT) and Unit Titles Act 1975 (NT).
ASIC MoneySmart also recommends reviewing cover regularly because underinsurance means the policy may not meet the full cost to rebuild, repair or replace what has been lost.
